
Introduction
Your finance team just flagged that nearly a third of last month's revenue leakage wasn't from customers firing you. It was from credit cards that expired, automated clearing house (ACH) failures, and billing glitches nobody caught. Involuntary churn is 20 to 40% of total losses for most B2B SaaS businesses. You are losing hundreds of thousands of dollars because your payment process is brittle.
For years, post-sales leaders stared at health score dashboards that told them a storm was coming but never bailed water. A red health indicator doesn't retry a card. A declining net promoter score (NPS) doesn't pause a subscription. In 2026, the market has split in two: tools that observe churn and tools that mechanically stop it. This guide helps you find a B2B SaaS churn management platform that protects recurring revenue by acting on the two churn engines eating your business right now.
Key Takeaways
Before diving into the mechanics of automated retention, here is what you need to know about the 2026 churn management landscape:
- Two distinct churn engines exist: Voluntary churn (product dissatisfaction) and involuntary churn (failed payments). Involuntary churn accounts for 20 to 40% of losses and is the fastest to automate and recover.
- Static health scores are obsolete: A dashboard flagging risk without triggering a recovery action is a reporting tool, not a retention system. The standard in 2026 is prescriptive automation.
- AI-native tools shift the workload: AI-native platforms automate high-volume recovery (dunning, save offers) so Customer Success Managers (CSMs) focus on high-touch enterprise relationships, not chasing declined cards.
- The checklist for a modern solution is non-negotiable: You need intelligent retry logic, cancel-flow save offers, dynamic health scoring that recomputes in real-time, and native Stripe/Braintree integration.
What a B2B SaaS Churn Management Platform Truly Is (Beyond Health Scores)
A B2B SaaS churn management platform is an operational system that stops revenue leakage by executing automated interventions. It mechanically resubmits a failed invoice when a bank returns a specific decline code.
Most teams are trapped with a legacy Customer Success (CS) suite that excels at static visualization. A customer health score is a predictive metric that measures a customer's engagement, but a score alone is a spectator. A true churn management platform, like the architecture Quivly provides, converts that signal into a tangible Action.
If a high-value account misses a payment, the platform auto-escalates to the Account Executive (AE) or Executive Sponsor while simultaneously triggering a dunning sequence. If a low-touch user hits the cancel button, a save offer deploys instantly.
The defining line is the execution layer. The platform must harmonize with your billing rails to arrest churn at the moment of the failed transaction.
This mechanical recovery fundamentally redefines the CSM role. Instead of digging through spreadsheets to find overdue invoices, the machine runs the playbook. The role of the human shifts to the high-stakes work: negotiating renewal terms or handling custom pricing. A tool like Quivly, with its Actions Feed and automated playbooks, ensures that while the machine retries the payment, the human only touches the account for a strategic conversation.
Health scores diagnose; churn platforms operate.
The Two Churn Engines: Distinguishing Voluntary from Involuntary Loss
The fastest path to revenue recovery is distinguishing between the customer who fires you and the customer who simply couldn't pay you.
| Dimension | Voluntary Churn (Customer Decision) | Involuntary Churn (Payment Failure) |
|---|---|---|
| Primary Cause | Dissatisfaction, poor product-market fit, AI-driven impatience with bad experiences | Expired credit cards, ACH declines, insufficient funds, network timeouts |
| Impact Scale | Critical long-term threat to product sustainability | 20 to 40% of total churn losses, a silent killer hiding in billing operations |
| Required Strategy | High-touch engagement, outcomes alignment, competitive displacement | Mechanical automation: automated dunning, card updaters, adaptive retry logic |
| Recovery Speed | Months (requires behavior change and product improvement) | Days (recovered the instant a successful charge is processed) |
Voluntary churn is a product problem that slashes growth rates over time. Each customer who cancels because your software didn't deliver the expected outcome signals a mismatch between what you sold and what they experienced. These losses compound. Every departed customer stops paying, stops referring, and often shares their frustration publicly.
Fixing this side of the equation demands genuine product work. Your team needs to understand why customers leave, ship improvements, and rebuild trust. It takes months, and the payoff is long-term sustainability rather than quick revenue bumps.
Involuntary churn is a billing operations problem hiding in plain sight. This is churn caused by expired credit cards, ACH declines, insufficient funds, and network timeouts, customers who want to keep paying but hit a payment wall. The transaction fails silently, the customer moves on, and revenue disappears without a single complaint filed.
What gets overlooked is how large this bucket gets. 20 to 40% of total churn losses stem from payment failures, not dissatisfaction. B2B companies with usage-based billing models are especially exposed because a single failed charge can cascade into service disruption.
The fix is mechanical, not strategic. Automated dunning sequences recover failed payments before customers notice. Account updater services pull fresh card details from card networks before expiration dates trigger declines. Adaptive retry logic learns which failed charges succeed on a second or third attempt and which need a different approach entirely. Most companies see these recoveries in days, far faster than any product-led retention effort.
The distinction matters because the resource demands are unrelated. Treating every lost dollar the same way means your team either over-engineers product fixes for billing failures or sends retention emails to customers who simply need a new card on file. Naming the category correctly is what makes the right response possible.
The 2026 Churn Landscape: Benchmarks, AI-Driven Cliffs, and the Outcomes Gap
The benchmarks for standard SaaS companies are moving, while AI-native products face a specialized retention cliff. Here are the three realities shaping the 2026 landscape:
- The stealthy GRR benchmark: Private B2B SaaS companies kept a median 91% of recurring revenue from existing customers in 2025, according to industry benchmarks. With increasingly intelligent competition, holding that Gross Revenue Retention (GRR) line requires blocking every hole in your bucket. Broader analysis puts median Net Revenue Retention (NRR) at 82%, highlighting that business expansion struggles when churn blunts base revenue.
- The AI cancellation cliff: The standard evaluation model is broken in the age of artificial intelligence (AI). Users no longer give you five bad experiences before leaving; they give you one. AI-native products now see radical volatility where median GRR drops to 40%, and if your seat is under $50 a month, gross revenue retention drops to 23%, with AI-native products losing more than three quarters of their revenue inside twelve months.
- The outcomes gap: Industry research identifies a critical 'outcomes cliff': customers are active but leaving because the product isn't delivering a transformative business impact. Static usage metrics won't catch this. Only a system mapping behavior to promised business value can bridge the gap.
How AI-Native Platforms Automate Prevention, Not Just Prediction
The real shift in 2026 is from predictive analytics to prescriptive autonomy. A predictive engine tells you Jane is probably leaving; an AI-native platform like Quivly prevents it by placing her on a temporary seasonal pause the moment she stops logging in. This is triggered automation, not a suggestion.
- High-volume engineered recovery turns an alert into a correction: Quivly reads bank decline codes, a 'do not honor' code triggers a specific timeline, while a 'contact issuer' failure generates a distinct set of customer-facing actions. This adaptive dunning logic recovers revenue that a static smart retry tool would abandon.
- A signal-aware system detects what a dashboard misses, a procurement change at a target company, surfaced by Quivly's Radar integration, can flag budget risk even when login frequency stays high. The platform connects that external market signal directly to the internal health model and actuates the next step: a recommended AE check-in or a contract revision alert.
The Feature Checklist: What to Demand from a Modern Churn Solution
Do not accept 'predictive analytics' as a feature; demand a closed-loop execution system. The core of any viable tool is intelligent payment retry logic, applying dynamic scheduling rules tied to specific gateway error codes so a 'do not honor' decline pauses the card rather than burning through retries.
- A dynamic health score recomputes every minute (not in daily batch) to surface real-time shifts.
- A modern solution functions as the operational brain of your tech stack, needing native Stripe and Braintree integration, behavioral cohort segmentation based on actions rather than company size or industry, and a co-pilot feed that drafts the specific follow-up email, cites the evidence behind the alert, and routes it to the correct CSM.
Comparing the Categories: Dashboard Suites vs. Point Tools vs. AI-Native Execution
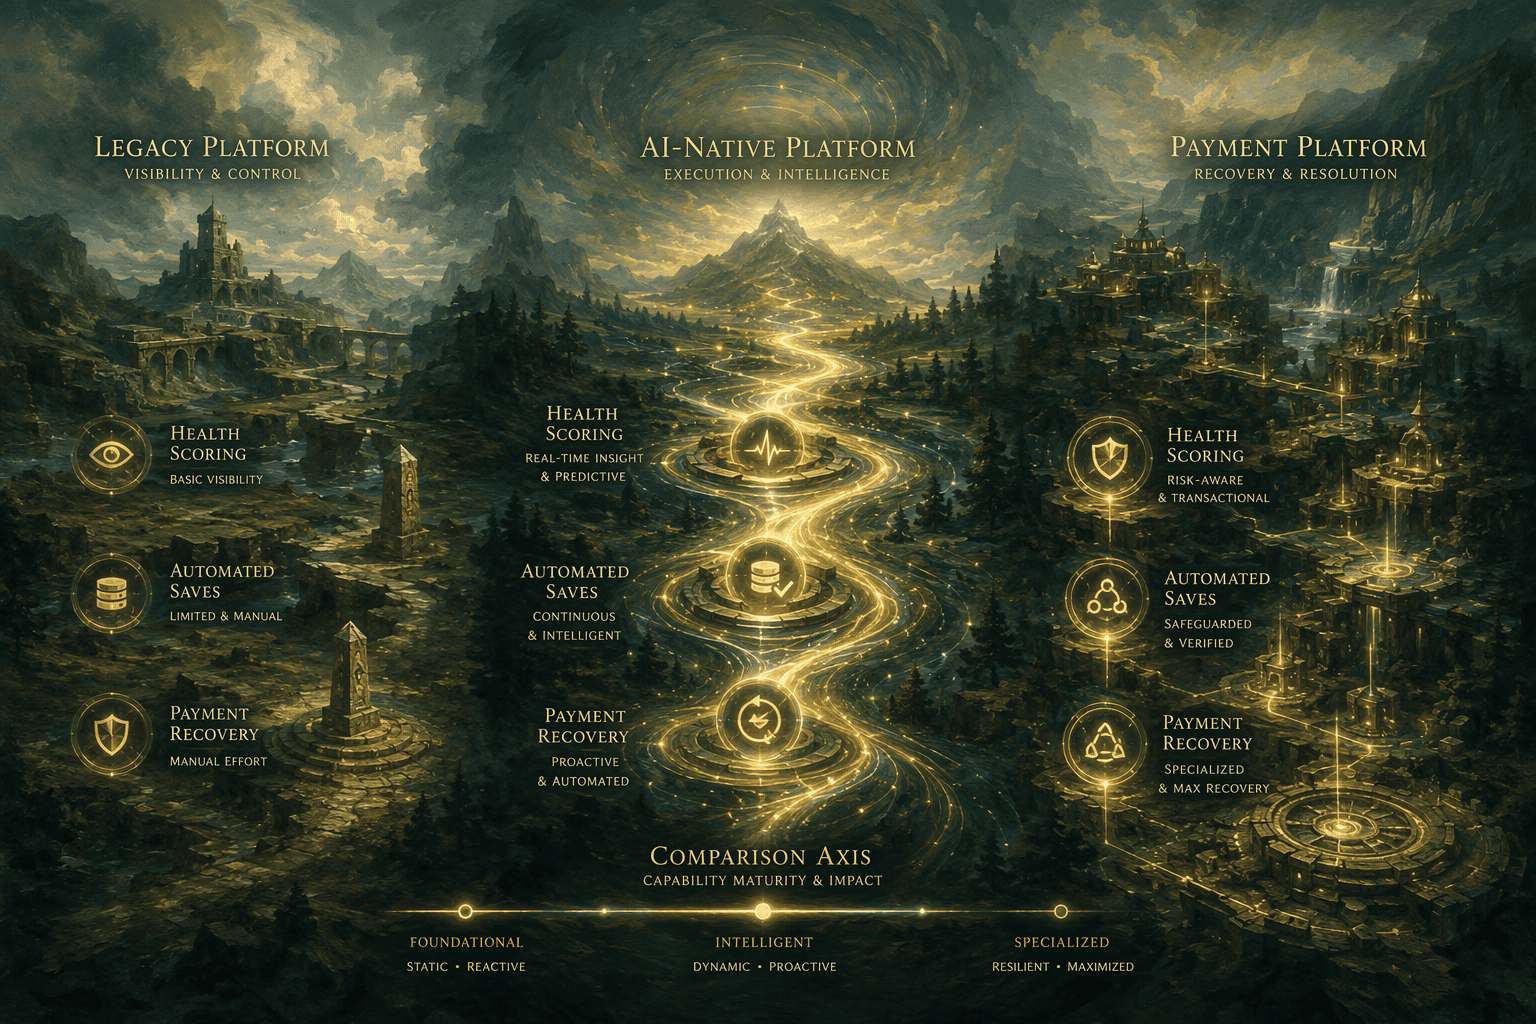
The decision between a legacy CS suite and an AI-native platform comes down to whether you want a historian or a firefighter.
| Capability | Legacy CS Suite (High-Touch Visibility) | Quivly AI (AI-Native Execution) | Payment-Recovery Point Tool |
|---|---|---|---|
| Primary Focus | Advanced health scoring (static snapshots), multi-step playbooks, high-touch visibility | Mechanical recovery via automated saves, expansion detection, and real-time signal processing | High-volume payment recovery and dunning management |
| Core Mechanism | Triggers actions based on time-based rules or manual thresholds within complex configurations | Actions Feed algorithmically surfaces risk and drafts next steps in a structured queue | Adaptive retry logic tuned for bank decline codes and card updater logic |
| Speed to Value | Weeks to months, intensive configuration often requiring a dedicated CS Ops admin | Days to live once sources are connected | Fast time to value for the billing churn subset |
| Data Freshness | Refreshes on a set schedule or user-triggered import | Health score recomputes every minute via connected, real-time sources | Heavily reliant on real-time billing gateway hooks |
Legacy dashboard-first suites are powerful systems of record. They catalog customer interactions, visualize trends, and give leadership a panoramic view of account health. The catch is that this view is always looking backward. A health score that refreshes nightly tells you something went wrong yesterday. It does not stop the cancellation that arrives at 10 a.m. on a Tuesday. Quivly starts from the other end of the problem. The Actions Feed ingests product usage, support tickets, and billing events and recompiles a health picture every minute. When a paying user hits a hard paywall three times in a single session, the system surfaces that account before the user opens a chat window to ask for a refund.
Legacy CS suites build their value on a careful chain of dependencies. A CS ops team maps the customer journey, defines dozens of health score components, weights them, and wires up playbooks that fire when a score crosses a threshold. That architecture works for enterprises with dedicated operations staff and a stable product surface. A startup running lean on a product that changes every sprint will break those configurations faster than it can fix them. Quivly removes the assembly step. It connects to your existing sources, begins processing signals, and populates a queue of concrete next actions in a couple of days. No playbook editor, no field mapping spreadsheet.
Payment-recovery point tools occupy a narrower lane and profit from that focus. If the bulk of your churn is involuntary — expired cards, retry failures, and downstream gateway declines — these tools are purpose-built for that problem. Their retry engines read bank decline codes and adapt timing and amounts to maximize recovery without triggering fraud holds. In that category, they often reach meaningful results within a few days of connecting payment hooks. The limitation is clear: they target the billing pipe and only the billing pipe. A customer who churns because they never adopted a core feature or because their champion left the company is invisible to a payment-specialist tool. You would still need a separate system, or a large manual CS effort, to see those accounts.
A surface-level integration pulls data on a fixed schedule and drops it into a dashboard. The platform becomes a passive observer without the ability to act when it matters. A native connection reads a live stream and pushes alerts into the tool your team already lives in, like Slack or a CRM, with a draft of the next message to send. The difference matters most in the first 90 days of a customer's lifecycle, when usage patterns are forming and an intervention today shifts retention for years. For most B2B SaaS teams, the fastest path to stopping cancellations starts with an AI-native platform that combines real-time signal detection with the mechanical execution to act on it immediately.
Enterprise Readiness: Deployment, Security, and Billing Integrations
A churn management system touches your money; rigor on security is the bare minimum. Deploying a platform like Quivly into the payment flow requires a distinct separation of concerns between observation and finance. The tool must be cloud-native with a clear private cloud path, backed by a documented SOC 2 policy and vendor risk management program. Quivly applies these security and privacy controls from ingestion to prediction.
- Integration depth determines whether you fix churn or cause billing chaos. A surface-level integration reads invoice events and sends dunning emails; a native integration reads the payment gateway's current state, respects its existing logic, and routes recommended actions to your A/R team without stepping on the treasury stack.
- The platform must harmonize with existing logic like Stripe Smart Retries, if your churn tool fires retries that conflict with the gateway's native logic, you create double-charges or shoulder declines that ruin customer trust. Quivly's billing connectors read the gateway's state directly and act as a coordinated layer that recommends routing next steps rather than conflicting with built-in treasury tools.
Measurable Outcomes: The Revenue You Should Expect to Recover
Switching from a dashboard to an actuated churn platform delivers an immediate, quantifiable return on investment (ROI) in the first billing cycle. About a third of SaaS churn comes from failed payments, not from customers deciding to leave. A dedicated automated churn management system can reclaim the majority of that lost cash. For a business with $10M in billing volume and a high rate of card delinquency, the realized revenue recovery from intelligent retries alone often pays for the cost of the software ten times over in a single quarter.
- Benchmark progress: Industry analysis shows the upper quartile of SaaS companies reaching 97% NRR, while the median private company hits 91% GRR. Getting to that 91% depends on mechanical payment recovery as much as product or sales efforts. The gap between your current retention and the benchmark is largely addressable through the 20 to 40 percent involuntary leak.
- Long-term revenue impact: By removing the noise of involuntary churn, Quivly surfaces expansion signals, for example, detecting that an engineering team has crossed a critical usage threshold and auto-deploying a playbook recommending a plan upgrade to the assigned CSM.
- Recovery solves the past; automated expansion secures the future.
Conclusion
A health score dashboard in 2026 is a luxury bill for information you already possess. The cancellation cliff is too steep for a reactive posture.
Solving churn now requires autonomous software that mechanically arrests revenue leakage at the point of failure. The data shows a massive chunk of your losses are involuntary; treating payment failure as a technical problem rather than a customer problem gives you a high-ROI win this month, not next quarter.
The standard is no longer observing why you lost them. It's building a system that simply doesn't let them leave.


